Carbon markets
EU ETS
Verified Carbon Standard
Verra
Voluntary Carbon Market
Regulation
Gold Standard
SBTi
ICVCM
CSRD
Article 6
VCM
ETS

The carbon market is no longer an experimental frontier—it’s becoming a fully-fledged pillar of global environmental finance. In 2025, it matured into a multi-billion-dollar ecosystem governed by a growing body of credible, specialised institutions. From disclosure frameworks and carbon credit standards to quality assurance bodies and trading platforms, the voluntary carbon market is becoming increasingly standardised, transparent, and trusted by investors, corporates, and regulators alike.
But with this growth comes complexity. A wide range of carbon market institutions now shape climate strategy and emissions accountability—from voluntary bodies like the Science Based Targets initiative (SBTi), to rating agencies like Sylvera, to regulatory frameworks such as the EU’s Corporate Sustainability Reporting Directive (CSRD). The challenge for most companies and investors? Understanding how these players interact, overlap, and influence both environmental disclosure and the credibility of carbon credits (also called carbon units).
At the heart of the complexity are evolving voluntary carbon market standards and frameworks. What’s the difference between SBTi and the GHG Protocol? How does the Integrity Council for the Voluntary Carbon Market (ICVCM) impact carbon credit quality? Which frameworks are being embedded into law, and which remain voluntary? With nearly 25,000 entities reporting environmental data to CDP in 2025 and more than 11,000 companies setting science-based targets under SBTi in 2025, the stakes are high for getting it right.
This article aims to map the landscape clearly: identifying the core institutions behind today’s carbon market, explaining their roles, and demystifying how they work together. Whether you’re a project developer, investor, or corporate sustainability officer, understanding this interconnected architecture is essential for understanding how to choose high-integrity carbon credits, as well as engaging in credible reporting and future-proof environmental claims.

Frameworks and standard setters
At the heart of the voluntary carbon market are the institutions that define what credible environmental action looks like. These frameworks establish the targets, metrics, and reporting norms that organisations use to measure, reduce, and communicate their emissions. They also form the foundation for understanding the legitimacy of carbon credit use and the broader concept of integrity in sustainability strategies.
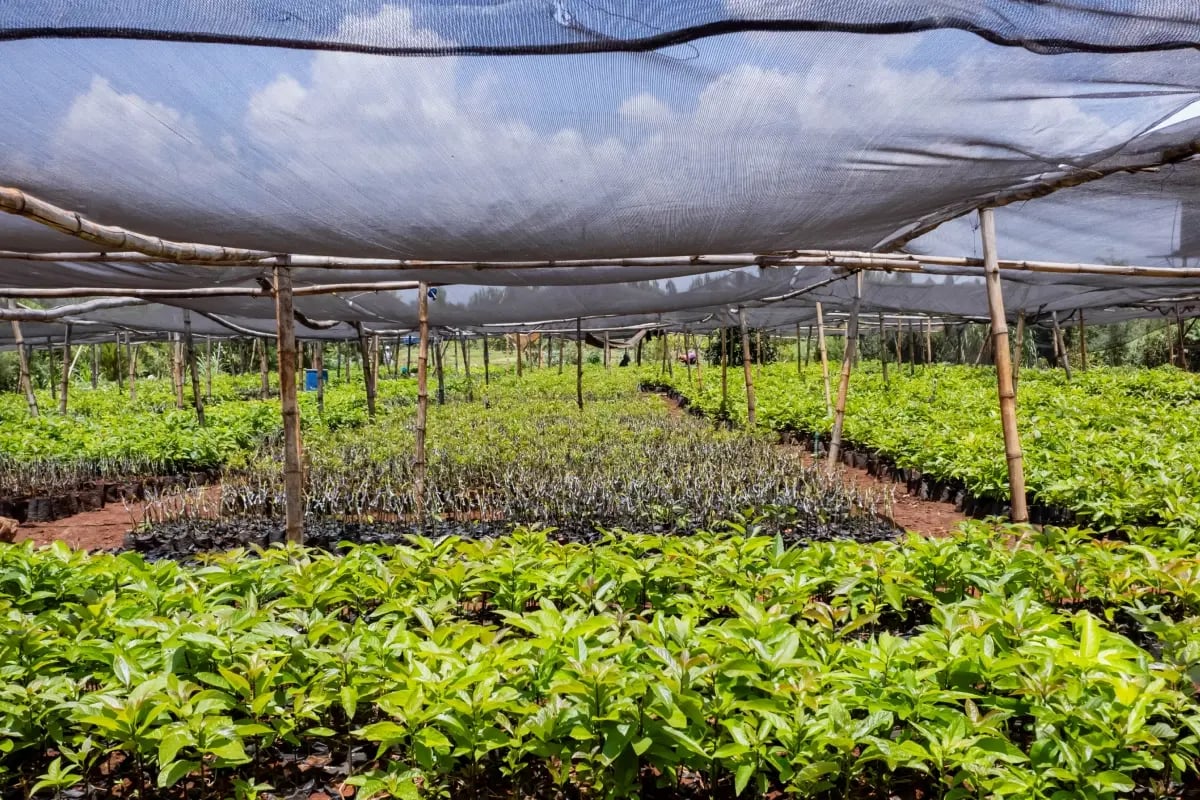 Tree seedlings nursery in Kenya, part of Hongera Reforestation Project, Green Earth.
Science Based Targets initiative (SBTi)
The Science Based Targets initiative (SBTi) is now a global authority on corporate decarbonisation. It helps companies set emissions reduction targets in line with planetary boundaries and is widely regarded as the anchor framework for aligning corporate action with environmental responsibility.
The SBTi helps companies translate environmental responsibility into measurable net-zero action by providing clear, scientifically grounded methodologies for setting emissions reduction targets across all scopes. Organisations must submit detailed emissions baselines, apply sector-specific pathways based on Intergovernmental Panel on Climate Change (IPCC) models, and undergo a rigorous validation process conducted by SBTi’s technical team.
Targets are only approved if they meet minimum ambition thresholds—typically aligning with the 1.5°C Paris Agreement scenario—and companies are required to publicly report progress and update targets every five years. This structure ensures that targets are not just self-declared ambitions but externally validated commitments, rooted in science and regularly scrutinised. Through this process, SBTi not only defines ambition but also embeds discipline and transparency, which is why it has become a global benchmark for credible decarbonisation strategies.
Read more: Carbon footprint measurement: a practical guide
By 2025, over 11,000 companies worldwide had committed to SBTi targets—up from 4,200 in 2023 and more than double the previous year’s figure. These companies represent nearly 39% of global market capitalisation in 2023, signalling a broad and growing shift towards measurable accountability. Crucially, SBTi emphasises reductions first and only allows the use of carbon credits in the final stages of an organisation’s sustainability journey, under the concept of beyond value chain mitigation.
Beyond value chain mitigation (BVCM) refers to the actions a company takes to reduce, remove, or avoid emissions outside its direct operations and supply chain. These include investing in high-quality carbon projects—such as reforestation, agroforestry, or clean cookstove initiatives—that generate verified carbon credits to compensate for emissions.
Read more: The Science Based Targets initiative and carbon offsetting: striking the right balance
Under the SBTi framework, BVCM is encouraged only after a company has made substantial progress on reducing its own emissions in line with approved targets. It is not a substitute for internal action but a complementary measure to accelerate broader environmental impact and contribute to global emissions reductions. BVCM is especially relevant in the voluntary carbon market, where companies seeking to support mitigation beyond their carbon footprint must ensure the integrity of the credits they purchase.
SBTi works closely with CDP and the GHG Protocol, and is structurally aligned with the Voluntary Carbon Market Integrity Initiative (VCMI), which defines how and when companies may use high-integrity carbon credits in external claims. This interconnectedness reinforces SBTi’s relevance in shaping the standards of the voluntary carbon market.

GHG Protocol
The GHG Protocol provides the global accounting standards framework for measuring and reporting emissions. Developed by the World Resources Institute and the World Business Council for Sustainable Development, it underpins most major frameworks, including SBTi, VCMI, and the EU’s Corporate Sustainability Reporting Directive (CSRD). It defines Scope 1, 2 and 3 emissions, and is used by companies and governments to quantify their carbon footprint in a standardised way.
More than 90% of companies reporting to CDP use the GHG Protocol to calculate and disclose their emissions. It has become the go-to standard not only for voluntary disclosures but also for regulatory regimes: The ISSB’s IFRS S2, California’s climate disclosure law, and the EU’s European Sustainability Reporting Standards (ESRS) all reference or incorporate GHG Protocol methodologies.
Its role in the carbon market is foundational. Without standardised emissions data, target setting, and offsetting strategies, credit use would lack consistency or comparability. The GHG Protocol brings order and transparency to this landscape, ensuring that organisations speak the same language when disclosing their impact.
ISO Standards (ISO 14064 and ISO 14067)
The ISO 14060–series is a set of internationally recognised standards developed by the International Organization for Standardization (ISO), an independent global body composed of national standard agencies. These standards provide clear, universally accepted rules for how organisations measure, manage, and verify their greenhouse gas emissions, both at the company level and within specific projects. It is used by companies, project developers, and auditors as a system to ensure carbon data is reliable and verifiable, and consistency is maintained across emissions data and carbon credit issuance.
Among the most relevant are ISO 14064-1, which guides how companies calculate and report their overall emissions, and ISO 14064-2, which applies to emissions reduction projects, such as those issuing carbon credits. ISO 14067 complements these by setting out how to calculate the carbon footprint of individual products.
Read more: SME carbon footprints: a practical guide
Major voluntary carbon standards like Verra and Gold Standard require that emissions reductions be verified through processes that align with ISO standards. On the regulatory side, the EU’s CSRD explicitly lists ISO 14064-1 as one of the approved methodologies for corporate GHG accounting, alongside the GHG Protocol. This global recognition makes ISO standards a backbone of credible environmental data—ensuring that reporting and crediting practices are objective, transparent, and technically sound.
If you're working in sustainability reporting, you might, for example, use the GHG Protocol to calculate emissions and then use ISO standards to verify that your process and data meet international benchmarks.
Corporate Sustainability Reporting Directive (CSRD)
The Corporate Sustainability Reporting Directive (CSRD) is the European Union’s new framework for mandatory environmental, social, and governance (ESG) disclosures, created to expand on the previous Non-Financial Reporting Directive (NFRD). Introduced in 2023 and entering into force in 2024, the CSRD dramatically expands the scope of sustainability reporting across Europe, requiring thousands of companies to disclose standardised information on their environmental impact, risks, and transition strategies.
Read more: What is CSRD and how does it affect your business?
The CSRD is designed to bring sustainability reporting on par with financial reporting, both in structure and assurance. Companies must report detailed metrics in line with the European Sustainability Reporting Standards (ESRS). Under the CSRD, companies are required to disclose information across four key reporting areas covering 12 categories:
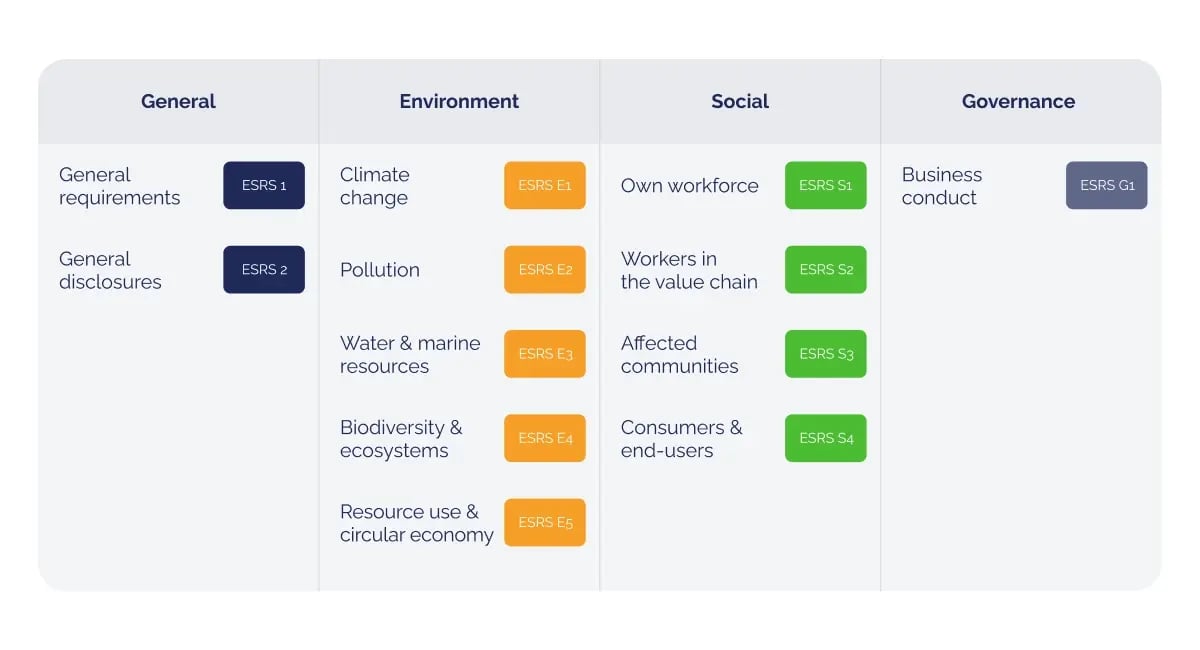 12 ESRS categories across four sustainability areas.
- General (mandatory): governance of sustainability matters, strategy and business model impacts, materiality assessment process, and policies, targets, and actions.
- Environmental (mandatory for climate category, only if material for others): climate change, pollution, water and marine resources, biodiversity and ecosystems, resource use and circular economy.
- Social (if material): own workforce, workers in the value chain, affected communities, consumers and end-users.
- Governance (if material): business conduct, anti-corruption, lobbying, management structure, etc.
Pillar 2 includes Scope 1, 2, and, critically, Scope 3 emissions. To ensure consistency, the CSRD allows companies to base their emissions accounting on widely recognised methodologies, such as the GHG Protocol and ISO 14064-1. This alignment brings voluntary frameworks into the heart of regulatory compliance.
Read more: Aligning with CSRD: the smart move for future-proofing your business
The CSRD also emphasises double materiality—requiring companies to disclose both how environmental factors affect their business and how their business affects the environment. For the voluntary carbon market, this means that use of carbon credits, offsetting strategies, and sustainability targets will be subject to formal scrutiny and assurance. It raises the bar on transparency and positions Europe at the forefront of standardised environmental disclosure.

ESRS (European Sustainability Reporting Standards)
The ESRS are the mandatory reporting standards that underpin the EU’s Corporate Sustainability Reporting Directive (CSRD). Developed by EFRAG, they operationalise the EU’s ambitious sustainability objectives by defining exactly what companies need to report and how.
ESRS E1 (Environment) includes comprehensive requirements for disclosing greenhouse gas emissions, targets, energy consumption, and reliance on carbon credits. It requires companies to disclose their entire emissions footprint, including Scope 3, and supports both the GHG Protocol and ISO 14064-1 as acceptable calculation methods. ESRS also formalises the concept of double materiality, requiring companies to report on both the financial and societal relevance of their environmental impact.
Read more: SME sustainability tools: How they help your business grow
SASB and IFRS/ISSB
The Sustainability Accounting Standards Board (SASB) developed industry-specific ESG metrics that are now embedded in the new global IFRS Sustainability Disclosure Standards, issued by the International Sustainability Standards Board (ISSB).
As of 2023, over 3,100 companies in more than 80 jurisdictions were using SASB standards, including nearly 75% of the S&P Global 1200—a sign of the framework’s authority with capital markets. The ISSB launched in 2021 to unify fragmented sustainability disclosure practices and published its inaugural standards, IFRS S1 (general sustainability) and IFRS S2 (emissions-related disclosures), in June 2023.
Read more: Trading carbon, trading up: the public companies transforming sustainability
These new global standards are rapidly gaining traction: 20+ jurisdictions, covering 55% of global GDP and 40% of public market capitalisation, have announced plans to align with ISSB guidance. The ISSB’s frameworks are structured around the former Task Force on Climate-related Financial Disclosures (TCFD) standards and include explicit requirements to disclose the use of carbon credits and emissions targets.

TNFD (Taskforce on Nature-related Financial Disclosures)
Building on the former TCFD structure, the TNFD addresses nature and biodiversity-related risks. Its final framework was released in September 2023 and already counts 320 organisations with $14 trillion in assets as early adopters.
Though still voluntary, TNFD is expected to influence future ESG reporting legislation and already aligns with standards like GRI, ISSB, and CSRD. As companies expand their disclosures beyond carbon, TNFD provides a structured way to account for ecosystem dependencies and land use risks—areas directly relevant to nature-based carbon projects.
Read more: Our favourite carbon-tracking apps, tools, and plugins (2025 edition)
Reporting and disclosure organisations
In the voluntary carbon market, transparency is everything. While target-setting frameworks like SBTi define ambition, it is reporting and disclosure organisations that make performance visible to stakeholders, investors, and regulators. These institutions shape how organisations document emissions, explain sustainability efforts, and disclose their use of carbon credits. They are essential to building trust and consistency across markets, and increasingly serve as the bridge between voluntary action and mandatory reporting.
CDP (formerly Carbon Disclosure Project)
CDP is the world’s largest platform for environmental disclosure, offering companies and cities a structured way to report on emissions, environmental risks, and mitigation strategies. Originally launched in 2000, CDP has grown into a core fixture of corporate sustainability evaluation, especially among investors.
In 2025, around 25,000 companies—representing two-thirds of global market capitalisation (~US$67 trillion)—disclosed through CDP. This marked a 25% increase from 2022 and a nearly 300% increase since the Paris Agreement. CDP is backed by more than 740 financial institutions with $136 trillion in assets, giving it enormous influence over how companies are evaluated and benchmarked on environmental performance.
CDP’s disclosures are aligned with the GHG Protocol, and it collaborates closely with SBTi, making it a natural choice for companies already pursuing science-based targets. In 2024, CDP began integrating the ISSB’s IFRS S2 climate disclosure standard and elements of the Taskforce on Nature-related Financial Disclosures (TNFD), allowing companies to report once and comply with multiple frameworks. It also plans to incorporate requirements from the CSRD, giving companies a centralised, investor-grade platform for comprehensive sustainability disclosure.
Read more: Carbon credit price guide: Understanding spot, forward, and market factors
GRI (Global Reporting Initiative)
The Global Reporting Initiative (GRI) provides the most widely used sustainability reporting framework in the world. Its standards are focused on an organisation’s impacts on society and the environment, and are built on a ‘double materiality’ principle—making them highly compatible with the EU’s CSRD.
As of 2025, 78% of the world’s 250 largest companies and 71% of 5,800 mid-sized companies reported using GRI standards. More than 10,000 organisations across 100+ countries use the GRI framework to report sustainability information. GRI’s emission disclosures are aligned with the GHG Protocol, and its updated 2021 standards require transparency on emissions, energy use, and environmental targets—including information about carbon credit use.
GRI is also working in close coordination with the European Financial Reporting Advisory Group (EFRAG) to ensure that its standards are interoperable with the ESRS. This makes GRI a strategic entry point for companies preparing for CSRD requirements, as well as those aiming to build trust through transparent voluntary reporting.
Credit certification bodies
While frameworks like SBTi and GHG Protocol define how emissions are measured and reduced, carbon certification bodies are responsible for verifying that emissions reductions or removals by carbon projects have actually occurred. These institutions create the methodologies that underpin carbon credit generation and issue verified credits following independent validation and monitoring. Their role is central to ensuring environmental outcomes are real, additional, and measurable.
 Carbon credit issuance by registry, source Sylvera.
Verra (VCS Program)
The Verified Carbon Standard (VCS), operated by Verra, is the most widely used carbon crediting programme in the voluntary market. As of 2023, Verra had issued over 1 billion verified carbon units (VCUs)—accounting for approximately 68% of global carbon credit issuance in recent years. Its registry includes more than 3,400 active projects across over 125 countries, spanning forestry, energy-efficient cookstoves, agriculture, and waste management. In 2024 alone, Verra issued 88.8 million credits.
Verra is considered one of the most influential credit certification agencies, setting benchmarks that many others follow. Its methodologies are comprehensive, publicly available, and updated through multi-stakeholder processes. Importantly, Verra is now working towards alignment with the Integrity Council for the Voluntary Carbon Market (ICVCM), seeking approval under the Core Carbon Principles (CCPs)—a label that signals the highest level of credibility in the market.
Verra has also piloted digital Monitoring, Reporting, and Verification (MRV) systems in partnership with tech providers like Pachama to improve efficiency and transparency, and offers co-benefit certification tools like CCB and SD VISta to ensure broader social and ecological value.
Read more: Preparing for the future: How SMEs can align with net-zero targets
Gold Standard
Founded by WWF in 2003, the Gold Standard is a leading certification body focused on delivering measurable, sustainable development outcomes alongside emissions reductions. Its methodologies require all projects to contribute to at least three UN Sustainable Development Goals (SDGs), making it especially attractive to buyers prioritising co-benefits.
Gold Standard credit issuance grew by 41% in 2023, making it the second most prominent standard after Verra. In 2024 alone, Gold Standard issued a total of 84.3 million units, up from 61.9 million in 2023.
While its scale is smaller, its reputation is strong: The organisation is known for higher stringency in additionality, local stakeholder engagement, and social safeguards. The Gold Standard is also approved under the ICVCM’s Core Carbon Principles—a key marker of credibility and alignment with market-wide integrity standards.
It has pioneered outcome-based financial instruments, developed methodologies for nature-based solutions and clean technology, and supported Article 6 readiness for host countries. Many corporates choose Gold Standard credits for their traceability and verified impacts.

American Carbon Registry (ACR) and Climate Action Reserve (CAR)
The American Carbon Registry (ACR) and Climate Action Reserve (CAR) are two of the most established crediting bodies in North America. Both are approved for use in the California cap-and-trade system, giving them a unique status as crossover standards between voluntary and compliance markets.
- ACR, established in 1996, has issued over 45 million credits to date and is particularly active in agriculture, forestry, and methane reduction projects. Its methodologies are technically rigorous, and its standards are aligned with ISO 14064. In 2023, ACR was designated CCP-Eligible by the ICVCM, reinforcing its high-integrity profile.
- CAR, launched in 2008, is best known for its role in developing the Forest Project Protocol used in California’s compliance market. It also pioneered project types like urban forestry and ozone-depleting substances. CAR credits can be transferred to Verra’s registry and are recognised in both voluntary and regulatory contexts.
 Green Earth team member checking coffee trees at the project site. Bulindi Agroforestry and Chimpanzee Conservation Project, Green Earth.
Both ACR and CAR are known for transparency, robust methodology review processes, and strong performance in agriculture and land use sectors—critical areas for scaling high-quality carbon projects.
Read more: From the ground up to space: seeing Green Earth’s impact in Uganda
Other notable carbon certification bodies
While Verra, Gold Standard, ACR, and CAR dominate the market, several other certification bodies also contribute to a growing and diversified landscape:
- Plan Vivo: Focused on community-led projects in the Global South, especially in agroforestry and smallholder systems.
- Global Carbon Council (GCC): Based in Qatar, increasingly active in the Middle East and Asia.
- Climate Forward: A newer initiative from CAR that certifies forecasted mitigation rather than retrospective reductions.
Integrity initiatives and market benchmarkers
As scrutiny of carbon offsetting intensifies, the role of oversight bodies and independent rating agencies has never been more critical. These institutions are shaping what defines high-quality carbon credits, ensuring transparency and restoring confidence in the voluntary carbon market. From global threshold-setting initiatives to cutting-edge analytics, these players are working to eliminate greenwashing and elevate standards across the board.
Integrity Council for the Voluntary Carbon Market (ICVCM)
If you’re wondering what the Core Carbon Principles are and who sets them, the Integrity Council for the Voluntary Carbon Market (ICVCM) is the authority leading that transformation. The ICVCM was created to set a unified, globally accepted benchmark for high-integrity carbon credits. In 2023, it launched the Core Carbon Principles (CCPs)—a set of 10 criteria that define the minimum requirements for credit quality, including additionality, permanence, quantification, and sustainable development safeguards.
So far, the ICVCM has approved Verra, Gold Standard, ACR, and CAR as CCP-Eligible, and by mid-2024, had granted full CCP-Approved status to credits from seven methodologies, unlocking over 27 million credits for CCP-labelling. This represents a foundational shift in how quality is benchmarked across the market.
With endorsements from the UN, IOSCO, and the World Bank, and with CCP requirements now being integrated into buyer guidelines and national regulations, ICVCM is fast becoming the cornerstone of carbon credit quality.
Read more: Green Earth’s cookstove projects: How they truly make a difference
Voluntary Carbon Market Integrity Initiative (VCMI)
The Voluntary Carbon Market Integrity Initiative (VCMI) guides companies on how to use carbon credits in a credible and responsible way. It tackles the demand side of the market, complementing ICVCM’s focus on supply.
In 2023, VCMI introduced its Claims Code of Practice, which outlines what companies must do to make credible environmental claims, such as net zero or carbon neutral. The Code is built on the principle that companies must first set science-based emissions targets, then report Scope 1–3 emissions publicly, before using any credits. Most importantly, credits used for claims must be CCP-approved, creating alignment between VCMI and ICVCM.
For companies asking how to align with the VCMI Claims Code of Practice, the answer starts with compliance: meet foundational emissions reduction requirements, disclose transparently, and only use verified high-integrity credits. Multinationals like Microsoft and Unilever have already piloted the Code, and governments in the UK and Canada are exploring its integration into green claims policy frameworks.

Carbon Offsetting and Reduction Scheme for International Aviation (CORSIA)
CORSIA stands for the Carbon Offsetting and Reduction Scheme for International Aviation. It is a global initiative led by the International Civil Aviation Organization (ICAO), designed to address the growth of emissions from international flights.
The aviation sector is responsible for a significant and growing share of global emissions, but reducing them directly is technically difficult in the short term. To bridge this gap, CORSIA requires airlines to offset any growth in their emissions beyond 2020 levels by purchasing carbon credits from approved projects.
Not all credits are accepted. CORSIA sets strict eligibility criteria to ensure that credits come from high-integrity projects—those that are real, additional, permanent, and independently verified. It currently recognises credits from standards such as Verra’s VCS (when paired with CCB) and the Gold Standard, both of which include frameworks for measuring biodiversity benefits.
 Voluntary States' Participation in CORSIA.
Credit rating agencies
As demand for accountability grows, independent credit rating agencies hired by buyers now play a vital role in assessing carbon credit quality at the project level. These organisations use satellite data, AI, and on-the-ground analysis to give independent scores that buyers can trust.
Sylvera
London-based Sylvera is one of the most influential players in this space. It rates credits on dimensions such as additionality, permanence, and co-benefits. Its platform is used by banks, corporates, and exchanges, and if you're seeking a Sylvera carbon project rating, it is now a baseline requirement for many buyers.
BeZero and Calyx Global
BeZero Carbon and Calyx Global each rated more than 300 carbon projects by 2023, providing one of the broadest datasets in the industry. BeZero’s ratings are embedded in Xpansiv’s CBL exchange, letting traders see credit quality instantly. Calyx, meanwhile, publishes not just project ratings, but also scores methodologies and registries—perfect for anyone who wants to dive deeper into systemic risk.
Renoster
Newer but rapidly gaining ground, Renoster is focused on forest and nature-based credits, especially in Africa. Its open-source, remote-sensing tools are helping democratise quality oversight, particularly for regions and developers that have traditionally been underserved.
Read more: Why we need to restore high-priority areas like Africa
For corporate buyers, investors, and platforms, these rating agencies provide a critical tool for understanding how to choose high-integrity carbon credits. By assigning risk-adjusted quality scores, they bring transparency and market discipline to an otherwise fragmented ecosystem.
Marketplaces
Behind every carbon credit transaction is a growing ecosystem of marketplaces and infrastructure providers that bring liquidity, transparency, and trust to the voluntary carbon market. These platforms ensure that credits are verifiable, tradable, and traceable—linking project developers to buyers through regulated systems that increasingly mirror mature financial markets.
Carbon credit exchanges
Xpansiv’s CBL exchange is the largest spot trading platform in the voluntary carbon market. In 2022 alone, it facilitated the trade of 116 million tonnes of carbon credits, worth $795 million. Since 2020, more than 300 million tonnes have changed hands on the platform, and it has consistently accounted for over 95% of global spot trading volume. Its success lies in standardising contract types and enabling price transparency via a public order book—key steps in making carbon markets behave like mature commodities markets.
To further professionalise the market, CBL now integrates third-party quality filters, including BeZero ratings and ICVCM compliance tags. In 2023, Xpansiv and CME Group partnered to launch new Core-Carbon-Principles-aligned futures products, allowing buyers to hedge risk and developers to lock in future prices.
AirCarbon Exchange (ACX) has pioneered the tokenisation of carbon credits. Operating out of Singapore and expanding into Abu Dhabi and Brazil, ACX enables instant settlement through blockchain-based infrastructure and securitises credits into tradable token classes (eg nature-based, tech-based, CORSIA-compliant). It has attracted over 130 institutional clients, including sovereign funds and commodity traders, and was recognised by Environmental Finance as the Best Carbon Exchange in 2021.
CME Group, the world’s largest derivatives marketplace, brought a new level of legitimacy to the market by launching physically deliverable carbon offset futures. By mid-2023, more than 200 million tonnes had been traded through CME’s GEO, N-GEO, and C-GEO contracts, which standardise delivery criteria for high-quality credits. These instruments provide forward price curves and reduce counterparty risk, factors essential for scaling investment into carbon projects.
Read more: High-quality carbon credits vs regular carbon credits: what sets them apart?
Registry infrastructure
Every verified carbon credit originates from a registry, where it is assigned a unique serial number and recorded in a central ledger. Registries like Verra, Gold Standard, IHS Markit, and APX act as digital custodians for issuance, retirement, and ownership transfer.
For example, Verra’s registry alone has issued more than 1.5 billion credits to date and logged over 800 million retirements, all publicly accessible through its online interface. These registries provide crucial transparency—project documentation, retirement certificates, and ownership history are now standard features.
Registries are also adopting emerging technologies to improve traceability. Several, including AirCarbon Exchange and Xpansiv, are experimenting with blockchain integrations that tokenise carbon credits while maintaining linkages to their original serials. Others, like S&P Global’s Markit Registry, offer meta-data tagging (eg ICVCM-aligned, co-benefits certified) to help buyers filter credits by quality criteria.
Efforts like the Climate Action Data Trust, co-led by the World Bank and IETA, are further pushing registries towards interoperability. This initiative will allow project and retirement data from multiple registries to be accessed via a unified public platform, improving trust and reducing the risk of double-counting.
Read more: The interconnected world of carbon: exploring key carbon market concepts
Together, these trading venues and registry systems underpin the structural integrity of the voluntary carbon market. By enabling standardised contracts, secure transfers, quality-tagged listings, and open-access tracking, they transform carbon credits from opaque assets into verifiable, investable instruments.
MRV technology providers
As demand grows for high-integrity carbon credits, so too does the need for more accurate, transparent, and scalable ways to monitor carbon projects. Traditional site visits and periodic reports are increasingly being replaced—or enhanced—by MRV (Monitoring, Reporting, Verification) technology providers that use satellite imagery, AI, blockchain, and remote sensing to validate environmental outcomes in real time, reduce costs, and enhance credibility. These innovations help certification bodies, buyers, and regulators ensure that credits are backed by tangible, verifiable results.
Pachama
Founded in 2018, Pachama has emerged as a leader in remote sensing and forest carbon MRV. The platform uses satellite data and machine learning models to monitor biomass changes, deforestation, and forest degradation, especially in nature-based solutions. Pachama works with crediting programs like Verra and has been instrumental in developing new digital measurement tools to speed up and de-risk verification processes.
Pachama also announced a partnership with ICVCM to explore how MRV data could support Core Carbon Principle alignment. According to the company, its MRV models can detect forest loss down to 10-meter resolution and reduce verification costs by up to 40% compared to traditional field audits.
Read more: Top sustainable technology trends in carbon projects for 2024
Regen Network
Regen Network is a blockchain-based MRV platform focused on regenerative agriculture and soil carbon. It operates an open-source protocol that allows developers to submit ecological monitoring data and receive automated verification via oracles and smart contracts. Regen issues credits on its own Regen Registry and tokenises them via its native blockchain, making them instantly tradable.
By integrating MRV and registry functions on-chain, Regen offers a compelling solution for small-scale or distributed projects, especially in agriculture, where data transparency and cost barriers have traditionally limited participation.
Read more: Reforestation and afforestation projects around the world: success stories and lessons learned
Open Forest Protocol
The Open Forest Protocol (OFP) provides decentralised, community-led MRV for forest projects, using satellite imaging, drone footage, and blockchain-based validation. Its model is particularly valuable for smallholders and Indigenous communities, who often lack the resources to engage with conventional certification systems.
OFP’s tools allow project developers to submit ongoing monitoring data, which is validated by a global network of independent verifiers and stored immutably on-chain. Their open-source platform supports integration with other registries and is being piloted for use alongside Verra’s registry and ICVCM-aligned methodologies.
Nonprofits, alliances, and advocacy groups
Behind the frameworks, certification bodies, and verification protocols lie the nonprofit organisations and advocacy groups that have shaped the voluntary carbon market from day one. These actors influence the development of standards, hold market players accountable, and ensure the system remains rooted in public trust, scientific evidence, and transparency.
NGOs: WWF, WRI, Environmental Defense Fund
Large international NGOs like the World Wide Fund for Nature (WWF), the World Resources Institute (WRI), and the Environmental Defense Fund (EDF) have been instrumental in founding and advising many of today’s most influential carbon market institutions.
- WWF co-founded both the Gold Standard and the Science-Based Targets initiative (SBTi), injecting environmental integrity and sustainable development into the DNA of credit certification and corporate target-setting frameworks.
- WRI co-authored the GHG Protocol, which underpins nearly every emissions reporting standard globally—from CDP and SBTi to CSRD. It also supports ICVCM and VCMI through technical advisory roles.
- EDF has been at the forefront of policy and science-based climate strategy since the 1980s. It played a central role in the creation of California’s compliance market and is currently advising on integration between voluntary credits and jurisdictional REDD+ systems.
These NGOs are not just observers—they are architects, ensuring that voluntary efforts align with broader environmental and social goals. Their presence in the governance bodies of SBTi, ICVCM, and VCMI helps reinforce consistency across carbon market institutions and discourage fragmented or conflicting standards.
Watchdogs and research platforms
As the market scales, independent watchdogs are essential to ensure transparency and prevent greenwashing. Two of the most established are Carbon Market Watch and Ecosystem Marketplace.
- Carbon Market Watch provides in-depth assessments of carbon credit quality, corporate claims, and policy effectiveness. In 2023, it published a widely referenced analysis of challenges in certain REDD+ project methodologies, contributing to a constructive dialogue around improvements in nature-based crediting approaches. These insights helped catalyse methodological updates by standards such as Verra and Gold Standard. The organisation also plays an active role in shaping EU policy on sustainable finance and environmental disclosures, reinforcing the credibility and consistency of carbon market frameworks.
- Ecosystem Marketplace, a Forest Trends initiative, is the go-to source for carbon market data. Its annual State of the Voluntary Carbon Market report tracks credit issuance, retirement, pricing, and buyer behaviour. In 2022, the report showed that over 500 million credits were issued and 170 million credits retired, with nature-based solutions leading demand. Ecosystem Marketplace also maintains a free, open-access carbon pricing database that is widely used by buyers, analysts, and journalists.
 Cumulative VCM Issuances and Retirements, 2002-2024.
Who needs what? A role-based breakdown
Different actors in the carbon market ecosystem rely on different standards, frameworks, and tools to operate with integrity, meet net-zero obligations, and avoid reputational risk. Below is a breakdown of who needs what and why.
Corporates
For companies looking to reduce emissions and make credible claims, the landscape is both rich and rigorous. The GHG Protocol is the foundational standard for emissions measurement, while the Science Based Targets initiative (SBTi) guides net-zero target-setting aligned with environmental science and operational discipline. Once internal targets are in place, companies turn to the Voluntary Carbon Market Integrity Initiative (VCMI) for guidance on external claims and offset use.
To understand how companies align with the VCMI Claims Code of Practice, they must meet criteria such as setting SBTi-approved targets, disclosing Scope 1–3 emissions, and using only high-quality, ICVCM-approved credits. CSRD compliance and transparent reporting round out the external-facing reporting suite, ensuring that climate-related actions are measurable, verifiable, and publicly accountable.
Read more: Overcoming sustainability challenges: practical solutions for your business
Investors
Institutional investors and ESG-focused funds need reliable data to assess risk and capital allocation. CDP scores offer a lens into corporate transparency and climate action readiness. The ISSB standards help standardise sustainability data within financial disclosures, making non-financial factors more comparable and decision-relevant.
For asset managers assessing the credibility of offset portfolios or fund-linked decarbonisation strategies, third-party verification is critical. This is where verifications like Verra and Gold Standard come in—helping avoid low-integrity assets and reputational exposure.
Read more: Carbon project financing: why carbon finance is the smartest bet for future-proof investing
Project developers
Carbon project developers sit at the heart of the supply side. They use standards like Verra and Gold Standard—the leading carbon certification bodies—to issue verified credits. These organisations provide methodologies and validation processes that developers must follow to ensure credits meet market expectations.
To quantify and report impact, developers rely on the GHG Protocol and ISO 14064, especially for methodology alignment and lifecycle accounting. Increasingly, partnerships with MRV tech providers such as Pachama, Regen Network, and Open Forest Protocol offer scalable, cost-effective ways to improve credibility, enable digital verification, and attract buyers who demand transparency.

Policymakers and regulators
Regulators need robust, transparent frameworks to ensure carbon claims align with national and international standards. The CSRD and accompanying ESRS provide the backbone for mandatory reporting across the EU. GRI remains a voluntary yet influential standard in global reporting frameworks.
On the quality front, regulators increasingly turn to the IICVCM and its Core Carbon Principles to assess whether credits can be included in corporate disclosures or public procurement schemes. The IFRS/ISSB standards ensure that environmental and sustainability data are insightful in financial statements, supporting systemic integration of environmental performance into broader regulatory architecture.
How it all connects
The carbon market isn’t governed by a single body, but rather by a network of interlinked institutions and frameworks, each playing a distinct yet connected role. Understanding how these frameworks interact is crucial for any company or investor navigating claims, disclosures, and credit procurement with confidence.
At the foundation lies the GHG Protocol, which sets the global standard for emissions accounting. It underpins how companies measure and disclose Scope 1, 2, and 3 emissions—data that feeds directly into both the SBTi and CSRD.

The SBTi uses the GHG Protocol as the basis for determining if a company’s decarbonisation targets are measurable and aligned with broader sustainability principles. Meanwhile, SBTi looks to the VCMI to define when—and under what conditions—carbon credits may be used to complement reductions. In this sense, VCMI acts as the bridge between internal targets and market-facing claims.
In turn, the VCMI builds on quality guidance from the ICVCM. Companies adhering to the VCMI Claims Code of Practice must ensure that any credits they use are approved under ICVCM’s Core Carbon Principles. This alignment ensures coherence across measurement, target-setting, and credit usage.
The credit supply side reflects similar integration. Standards like Verra and Gold Standard develop methodologies and issue credits, which are then assessed for Core Carbon Principle eligibility by the ICVCM. Those same credits are also subject to third-party scrutiny from rating agencies like Sylvera, offering buyers an additional layer of risk-adjusted evaluation.
If you’re wondering about the difference between SBTi, VCMI, and ICVCM frameworks, the simplest breakdown is this:
- SBTi tells you how much to reduce,
- VCMI tells you how to credibly use offsets alongside reductions,
- ICVCM defines what counts as a high-integrity offset in the first place.
Together, they create a coherent system that spans emissions measurement, reduction strategies, offset use, and market quality assurance. It’s a layered ecosystem—but one increasingly aligned around common principles of accountability, transparency, and integrity.
On the reporting front, the CSRD requires companies to disclose emissions, risks, and transition plans using structured data frameworks. Much of this input comes via GRI disclosures, CDP submissions, and GHG Protocol data—while the ISSB convergence ensures alignment with global financial reporting standards.
Read more: What makes Green Earth’s reforestation projects unique?
Navigating the market with confidence
The voluntary carbon market may seem complex, but it’s collaborative. From frameworks that define credible action, to institutions that verify project quality, to platforms that bring transparency to transactions, every layer of this ecosystem exists to ensure that emissions reductions are measurable, traceable, and trustworthy.
Understanding the roles and relationships of these actors isn’t just an academic exercise. It’s essential for any company or investor serious about making environmental claims that stand up to scrutiny. And it’s how we collectively shift the conversation from ambition to accountability.
At Green Earth, we work at the intersection of these frameworks, developing high-quality, nature-based carbon projects that meet the world’s rising bar for integrity. Our reforestation and biodiversity restoration initiatives are independently verified by Verra or the Gold Standard and designed to support companies in achieving their science-based targets while delivering real, lasting environmental outcomes.
 Close-up of a Green Earth team member planting a tree seedling at the project site. Hongera Reforestation Project, Green Earth.
If your company is on the journey to decarbonisation, we’re here to be your partner, not just in credits, but in credibility. Because a functioning, trustworthy carbon market doesn’t just enable compensation—it enables transformation.